 https://www.gpayments.com/blog/wp-content/uploads/2026/10/Card-payments-scaled.jpg
1707
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-16 15:31:312026-10-16 15:31:32How to Authenticate Stored-Card Payments When Account Takeover Is Suspected
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/One-3DS-Server-Multiple-Acquirers-scaled.jpg
2560
1928
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-16 10:22:222026-10-16 10:22:23Using One 3DS Server Across Multiple Acquirers
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/RBA-Review-Feedback-scaled.jpg
1707
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-15 09:42:512026-10-15 09:43:20What the RBA Review Feedback Means for Card-Not-Present Authentication
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/3DS-Challenge-Indicator-Value-scaled.jpg
1707
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-14 10:29:282026-10-14 10:29:29When Merchants Should Request a 3DS Challenge, and When to Ask for None
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/SMS-OTP-scaled.jpg
1528
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-14 09:50:162026-10-14 09:50:17What Regulators Retiring SMS OTPs Means for 3D Secure Challenges
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/Biometric-Payment-Authentication-scaled.jpg
1709
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-14 09:33:232026-10-14 09:33:24How Passkeys, Network Tokens, and EMV 3DS Fit Together at Checkout
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/3D-Secure-Authentication-Flow.png
887
1774
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
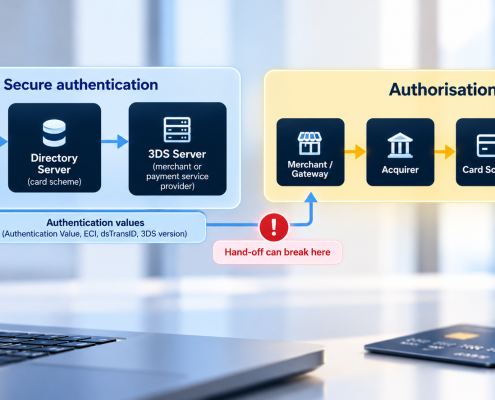
Zeeshan Rizvi2026-10-13 13:55:352026-10-13 15:12:10Why Authenticated Transactions Lose Their 3D Secure Protection at Authorisation
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/3D-Secure-Against-Card-Testing-Attacks-scaled.jpg
1439
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-09 11:59:432026-10-09 12:27:14Where 3D Secure Helps Against Card Testing, and Where It Doesn’t
 https://www.gpayments.com/blog/wp-content/uploads/2026/10/Financial-Analytics-Dashboard-scaled.jpg
1440
2560
Zeeshan Rizvi
https://blog.gpayments.com/wp-content/uploads/2022/05/Logo_Black_on_White_lowres-300x80.png
Zeeshan Rizvi2026-10-09 11:57:042026-10-09 11:57:05How Merchants Should Measure 3D Secure Performance